The Folio · November 2026Pan-India · more than 200 lawyersMumbai · New Delhi · Bengaluru
White & Brief — Advocates and Solicitors Contact →
The Folio · Practice · Transactions

Corporate & M&A

The practice that moves control of a company from one set of hands to another: acquisitions, mergers, schemes of arrangement, joint ventures, and the shareholder arrangements that have to hold afterwards.

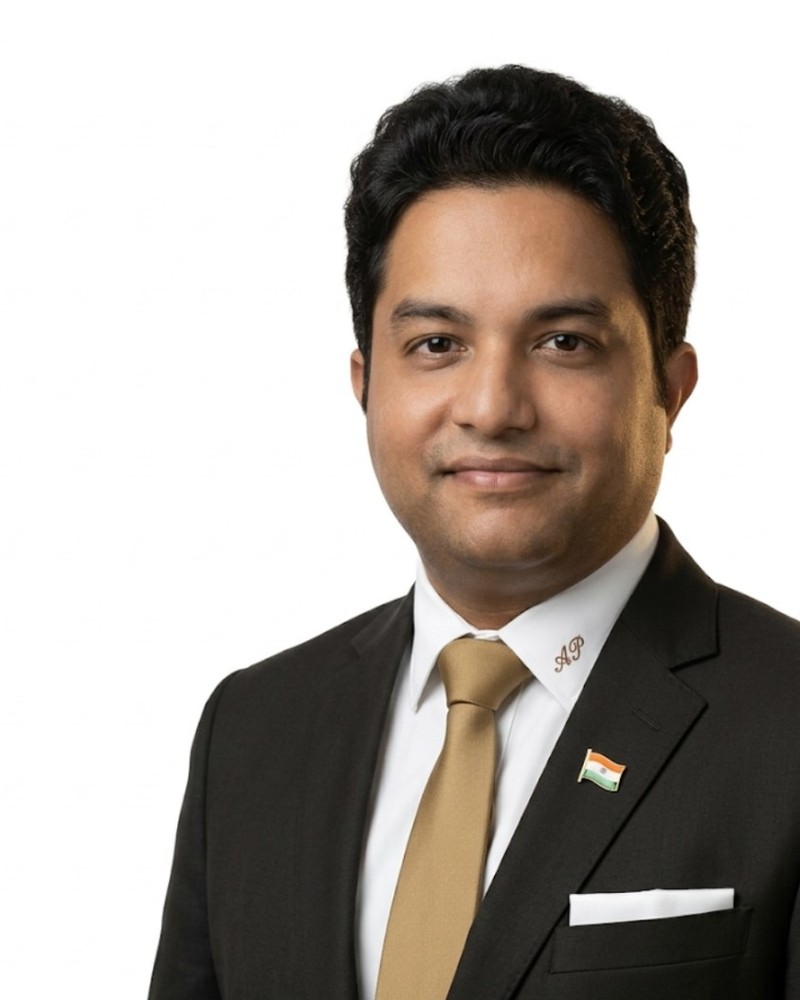
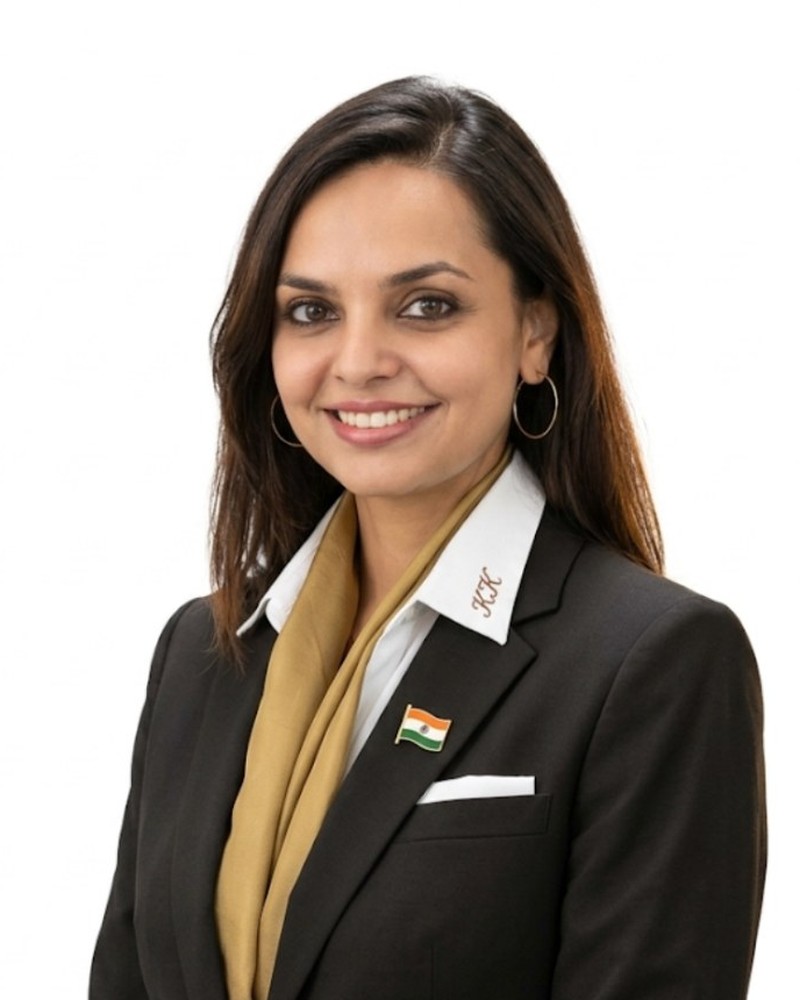
Led by Mr. Anupam Prasad, with Mr. Arvind Gurumurthy, Ms. Khushboo Butail Karol.

Domestic and cross-borderSigning to closingUS and Japanese clients
Corporate & M&A.
Corporate & M&A.
Share and asset acquisitionsSchemes of arrangementJoint venturesMerger controlDue diligenceAuctionsWarranties & indemnitiesIntegration
TechnologyHealthcareManufacturingConsumerFinancial servicesMediaEnergy
I · The Brief

What clients bring us.

Since 10 September 2024 a transaction valued above ₹2,000 crore requires merger clearance where the target has substantial business operations in India, whatever its turnover. That threshold sits above everything else a buyer must survive: a seller who will not warrant what he cannot verify, minority holders with veto rights buried in an old shareholders' agreement, a scheme of arrangement that has to satisfy the National Company Law Tribunal, and a condition precedent nobody can put a date against. Deals rarely fail on price. They fail in the space between signing and completion, on things that were known and left unresolved.

You get a deal run to the closing date rather than to the document. Diligence reports what will change the price or the conditions, and reports it in the first week rather than the last. We draft and negotiate the share purchase, business transfer, scheme and shareholder documents, and hold the merger control, sectoral and stamp duty positions on the same file, so that no filing is discovered after signing. Where a matter reaches the National Company Law Tribunal, the people who drafted the scheme argue it.

II · The Remit

What we handle.

Before courts, tribunals, regulators and counterparties across India.

  • IShare and asset acquisitions, and business transfers on a slump sale basis
  • IIMergers, demergers and schemes of arrangement before the National Company Law Tribunal
  • IIIJoint ventures, shareholders' agreements and promoter arrangements
  • IVLegal and regulatory due diligence, with the material findings reported in the first week
  • VMerger control assessment and filings under the Competition Act, including deal value notification
  • VIGroup reorganisation, holding structure design and re-domiciliation
  • VIIBuy-side and sell-side auction processes and transaction management
  • VIIIManagement incentive plans, sweat equity and employee stock option schemes
  • IXWarranty, indemnity and escrow negotiation, and completion accounts
  • XPost-closing integration: contract novation, licence transfer and employee transition
  • XIBoard and shareholder process, and Companies Act compliance
  • XIIMinority protection, and oppression and mismanagement proceedings
III · The Record

Types of work, without client names.

Described without client names, as the Bar Council of India rules require.

I

A bank

An Indian bank held two businesses in subsidiaries and wanted them inside the flagship company. We ran the scheme of arrangement: the share exchange, the classes of shareholders and creditors, the regulatory intimations, the petitions and affidavits, and the hearings that follow them. The two subsidiaries were folded into the flagship company.
II

A French engineering group

A French engineering group set out to buy an Indian structural and civil engineering consultancy, a business that carries its value in its people and its live appointments rather than in anything on a fixed asset register. We diligenced the appointments and asked what would happen to each of them on a change of control, then negotiated the acquisition documents for the buyer on that basis.

III

An Asian services group

An Asian services group agreed a purchase it could not settle in cash alone. We structured and documented mixed consideration, part cash and part shares, with the valuation basis, the securities issue mechanics, the lock-in and the escrow that a share element requires on both sides. The acquisition settled on that mixed cash-and-share consideration.

IV

A group with operations in India

We rebuilt it: the transfers between entities, the tax and exchange control positions, the corporate approvals in each jurisdiction, and a sequence that left the operating company undisturbed. The structure was re-domiciled into India.

IV · The Method

How we work.

A corporate deal has one date that matters and a hundred things that can move it. We keep a conditions list from the first draft, with an owner and a date against every line, and circulate that rather than the redline. Findings are priced as they are found instead of being saved for a report. One partner holds the transaction, and the tax, competition, employment and property views reach that partner before they reach you. On completion day the documents are signed in one room, or on one call, in an agreed order.

What to send us firstThe first useful documents are the shareholding pattern, the current shareholders' agreement and two years of board minutes. Read together, they usually show what will hold up signing and what will hold up closing, which are seldom the same thing.
V · The Corridors

Where this practice travels.

New York

New York

India · United States and Canada. from Wall Street to Dalal Street.

Tokyo

Tokyo

India · Japan. the Rising Sun and the Gateway.

VII · The Pen

Forthcoming from the partners.

Mr. Anupam Prasad

What Japanese and US acquirers ask about Indian targets after the 2026 tariff changes

Mr. Anupam Prasad

Merger control in India: living with the deal-value threshold

Mr. Arvind Gurumurthy

Overseas acquisitions by Indian mid-caps under the ODI rules

The Team

The lawyers on the file.

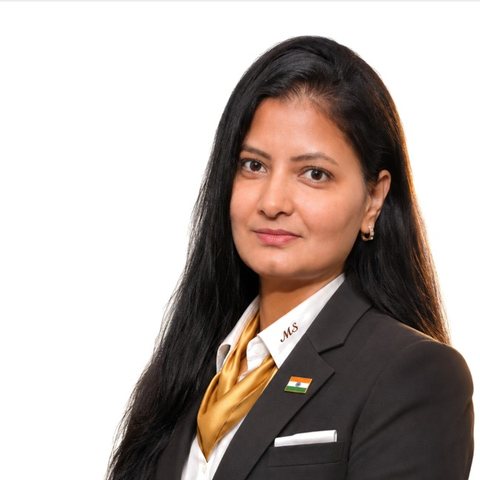
Ms. Manshi Shah
Ms. Manshi Shah
Senior Associate
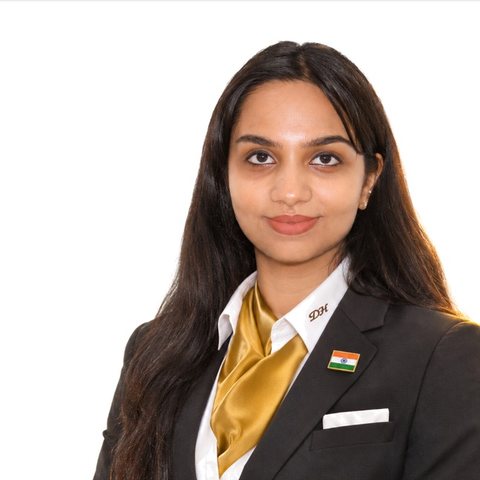
Ms. Divya Haridas
Ms. Divya Haridas
Associate
Ms. Aachal Mukherjee
Associate

Under the rules of the Bar Council of India, White & Brief may not advertise or solicit work. By continuing you confirm that you are seeking information about the firm on your own initiative, and that nothing on this site is legal advice.